
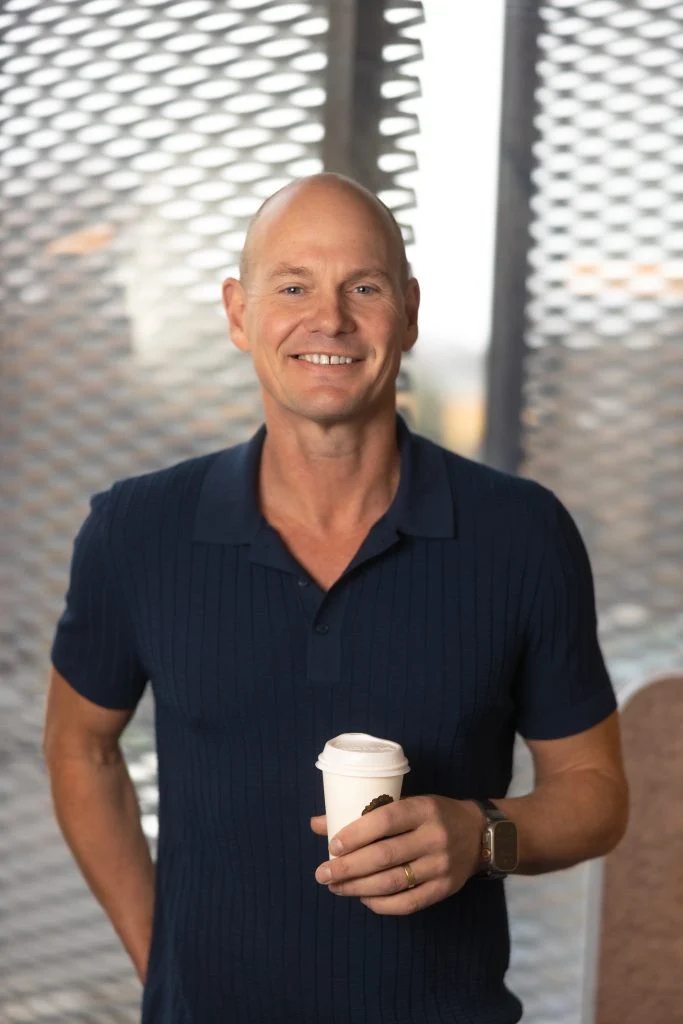
Cam McLellan says Australian prices do not move on a fixed 18-year
National home values fell 0.9% in August 2026, yet OpenCorp founder Cam McLellan argues that does not prove Australia is heading for a property crash tied to an 18-year land cycle.
The theory traces back to a Chicago study published in 1933. It claims land values follow a pattern of growth, a mid-cycle wobble, more growth and then a crash over roughly 18 years.
Because 2026 is 18 years after 2008, some property commentators have used that timeline to argue Australia is due for a major reset. McLellan rejects that approach and says it has little relevance to the local market.
“Property markets are run on supply, demand, affordability and consumer confidence. None of those four keep to a timetable,” OpenCorp CEO Cam McLellan said.
He also disputes the starting point behind the forecast. McLellan says Australia did not have a genuine property crash in 2008, so using that year as the base for a 2026 downturn is flawed.
Instead, he argues Australian downturns have reflected changing interest rates, credit conditions, unemployment and offshore shocks. In his view, those forces do not follow a calendar-based rhythm.
Cotality data shows city and price-band splits
Cotality figures released in September 2026 showed Sydney home values fell 7.1% from their February peak. That decline came as national values dropped 0.9% in August.
The same data showed different parts of the market moving in opposite directions inside the same cities. Upper quartile and lower quartile markets did not weaken at the same pace.
Nationally, upper quartile values fell 3.2% over the three months to July. Over that same period, lower quartile values rose 0.3%.
McLellan says that split makes broad national timing theories less useful. According to his view, investors need to look at individual markets rather than assume every suburb and price point will move together.
He says the current softness reflects policy uncertainty that has hurt consumer confidence, not a fundamental break in the housing market. OpenCorp also expects a structural supply shortage to continue because land release remains tight and the construction sector still faces trade constraints.
As a result, McLellan argues the more reliable approach is to identify undervalued capital city markets and specific growth corridors. He points to limited land supply, rising infrastructure investment and population growth as the main factors to watch, rather than a theory built on a 1933 US study.